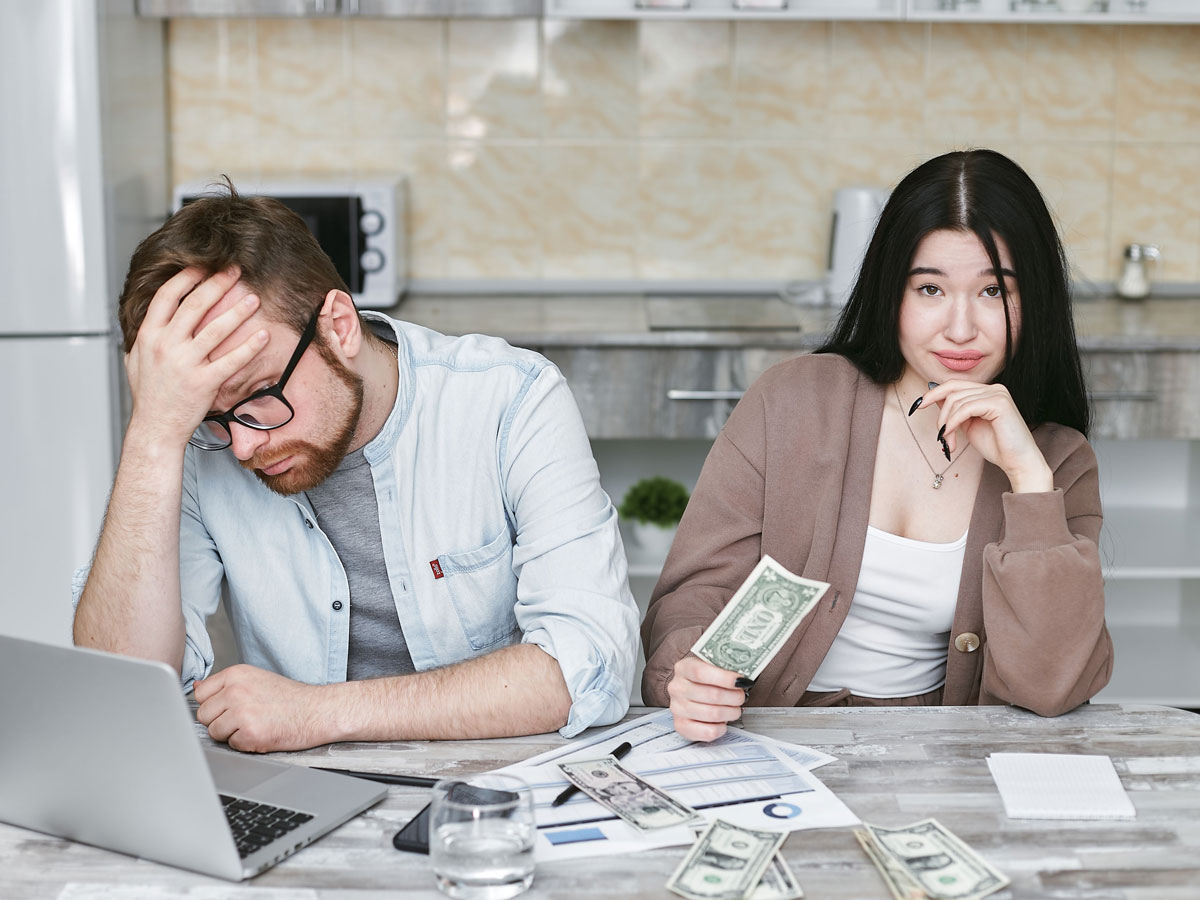
 Photo by Mikhail Nilov on Pexels
Most people think money problems cause stress because of math. The balance is too high. The paycheck is too small. The bills arrive too fast. That is true, but it is not the whole story. A lot of financial pain is not happening in a spreadsheet at all. It is happening in the body, in the nervous system, and in the private story a person tells about what their debt says about them.
That is why so many people do not just avoid statements, calls, and budgeting apps. They avoid themselves. In the middle of that avoidance, they may start researching options like Freedom Debt Relief vs National Debt Relief reviews, not only because they want answers, but because they want relief from the emotional pressure that builds when money starts to feel personal.
Financial shame is different from simple regret. Regret says, “I made a bad choice.” Shame says, “I am bad with money. I am irresponsible. I am hopeless.” That shift matters more than people realize. When the problem moves from behavior to identity, it becomes much harder to solve.
Psychologists often draw a line between guilt and shame. Guilt tends to focus on a specific action, while shame targets the whole self. That difference helps explain why guilt can sometimes push a person toward repair, while shame often pushes them toward hiding, withdrawal, and self protection. The American Psychological Association’s discussion of guilt and shame highlights this distinction clearly, and it helps explain why shame so often freezes action instead of motivating it.
The hidden damage of financial shame is that it creates a loop. You feel ashamed, so you avoid looking at your bank account. Because you avoid it, you miss a due date, forget a notice, or spend emotionally to escape the discomfort. Then the situation gets worse, which creates more shame. That new shame leads to more avoidance. Soon, the original money problem is no longer the only issue. The real threat is the cycle itself.
This is the part many personal finance conversations miss. They assume people fail to act because they do not know what to do. In reality, many people know the next smart step. They know they should call the lender, open the bill, cancel the subscription, or ask for help. The barrier is not always knowledge. Often, it is emotional paralysis.
Shame narrows attention. It can make even small tasks feel loaded with danger, as if opening an email could confirm every fear you already have about yourself. That is why a person can be highly capable at work, responsible with family, and still feel completely powerless when facing personal debt.
From the outside, financial avoidance can look immature or careless. From the inside, it often feels more like threat management. The brain and body are trying to protect you from more pain, embarrassment, or exposure. That protection just happens to backfire.
This matters because people tend to shame themselves for the coping response too. They are ashamed of the debt, then ashamed of avoiding the debt, then ashamed of being ashamed. At that point, the emotional load becomes heavier than the numbers themselves.
Research on shame has consistently linked it with withdrawal and defensive behavior, which makes this pattern easier to understand. If shame is telling you that exposure is dangerous, your system will naturally try to reduce exposure. That can mean not checking balances, dodging conversations, or pretending things are fine until they are not.
The cost of shame is not limited to fees, interest, or damaged credit. It can spill into sleep, relationships, concentration, and mental health. People under financial shame often become more irritable, more isolated, and less honest, even with people they love. Not because they are deceptive by nature, but because shame thrives in secrecy.
Secrecy also drains energy. Keeping up appearances takes effort. So does rehearsing excuses, hiding purchases, screening phone calls, and carrying constant dread in the background. Over time, that kind of stress can wear down a person’s ability to think clearly and make steady decisions.
In other words, financial shame does not just sit beside hardship. It actively multiplies it.
People often believe they need a full financial turnaround to feel better. Usually, they need something more basic first. They need enough emotional safety to re enter reality. That may start with one very small act of contact. Open one envelope. Log in to one account. Write down one total. Tell one trusted person the truth.
This is not about pretending debt is no big deal. It is about separating your worth from your circumstances so your problem solving ability can come back online. Shame says, “Hide until you become acceptable.” Recovery says, “You do not become more capable by disappearing.”
Self compassion can sound soft in money conversations, but it is actually practical. If shame shuts down action, compassion makes action more possible. That does not mean excusing harmful habits. It means responding to yourself in a way that supports change instead of collapse. NAMI’s guidance on self compassion is a useful reminder that kindness toward yourself is not denial. It is a tool for staying engaged.
One of the most powerful shifts a person can make is changing the question. Instead of asking, “What is wrong with me?” ask, “What happened that made this hard to face?” That question opens the door to useful answers. Stress, family modeling, job loss, medical bills, divorce, fear, perfectionism, and plain exhaustion all shape financial behavior.
Once shame stops being the narrator, you can start seeing the real factors involved. And once you can see them, you can work with them.
Financial shame wants silence, hiding, and self attack. The way out is not instant confidence. It is honest contact. Not with some ideal future version of yourself, but with the person you are right now, who still deserves help, dignity, and a chance to repair what has been weighing them down.


Discover our other works at the following sites:
Danetsoft is a global web agency headquartered in Indonesia, specializing in web development, managed hosting, and web publishing platform.


 [email protected]
 Magelang, Central Java
© 2026 Danetsoft. Powered by HTMLy