 Photo by Yan Krukau on Pexels
Managing money has never been simple, but it used to depend mostly on manual work, memory, and a lot of guesswork. Today, AI is changing that in practical ways. It can sort transactions, spot unusual spending, help us save automatically, and give us a clearer view of where our money is going.
That does not mean AI should run our finances for us. What it does mean is that we can use better tools to make better decisions. Instead of digging through bank statements or trying to remember where every dollar went, we can get faster insights and more useful alerts. That saves time, reduces stress, and helps us act before small issues turn into bigger ones.
In this article, we will look at the most useful types of AI financial tools, how they work, and why they matter in everyday life. We will also look at the features worth paying attention to before we trust any app with our financial data.
Money creates a huge amount of data. Every purchase, transfer, bill payment, refund, and investment change adds to the picture. Human beings can understand that information, but not very efficiently when the numbers pile up. AI is good at scanning large amounts of data quickly and finding patterns we might miss.
That is especially useful because financial decisions are often made when we are busy, distracted, or under pressure. We might not notice a subscription fee that increased, a spending category that is creeping up, or a portfolio that is too concentrated in one area. AI helps turn raw account activity into something more understandable.
The real value is not that AI makes decisions for us. The value is that it gives us a clearer view, so our decisions are based on facts rather than rough guesses.
Budgeting is usually the first place people notice the benefit of AI. Traditional budgeting takes effort, because we need to sort every transaction manually and check spending often. AI removes a lot of that work.
Many budgeting apps now connect to our bank accounts and credit cards, then sort transactions into categories such as groceries, dining, transportation, rent, travel, or entertainment. This might sound like a small feature, but it saves a lot of time.
The bigger advantage is visibility. Once spending is organized, we can quickly see where our income is going. That makes it easier to spot habits that are more expensive than they seemed at first.
Some tools also learn from our patterns. If we tend to spend more on weekends or buy coffee on certain days, the app may point that out. These insights can be surprisingly useful, because small recurring habits often have a bigger financial effect than we expect.
AI budgeting tools can also send alerts when spending moves off track. If a category starts running over budget, if a bill looks higher than usual, or if a recurring payment changes, the app can flag it.
That matters because small leaks in a budget are easy to ignore until they become real problems. A good alert gives us a chance to correct course sooner.
Recurring charge detection is especially helpful. Many people forget about old app subscriptions, streaming services, memberships, or trial periods that turned into monthly costs. AI can help uncover those charges and show us whether they are still worth keeping.
These tools are useful for beginners, busy households, people with multiple accounts, and anyone who wants more control without building a budget from scratch. They are also good for people whose income or expenses change from month to month, because they make it easier to keep track without constant manual updates.
Saving money is important, but it often gets pushed aside when life gets busy. AI can make saving feel less like a chore and more like a background process.
Some savings apps watch our balance, income timing, and spending patterns, then move money when the timing looks safe. That might happen after payday, after a lower-spending week, or through small round-ups from purchases.
This approach works well because it fits real life. Instead of asking us to make large transfers that could strain the budget, the system looks for small opportunities that do not disrupt daily spending.
Other tools focus on specific goals. We can set targets for an emergency fund, a vacation, a car repair fund, or a house down payment. AI then calculates how much we should save each week or month to stay on track.
That makes the goal feel more concrete. We are no longer just saying that we want to save more, we can see a path forward and measure progress along the way.
Many people do not fail to save because they are careless. They fail because saving is disconnected from everyday life. AI helps close that gap by making saving automatic and easier to maintain. Consistency matters more than big bursts of effort, especially over the long run.
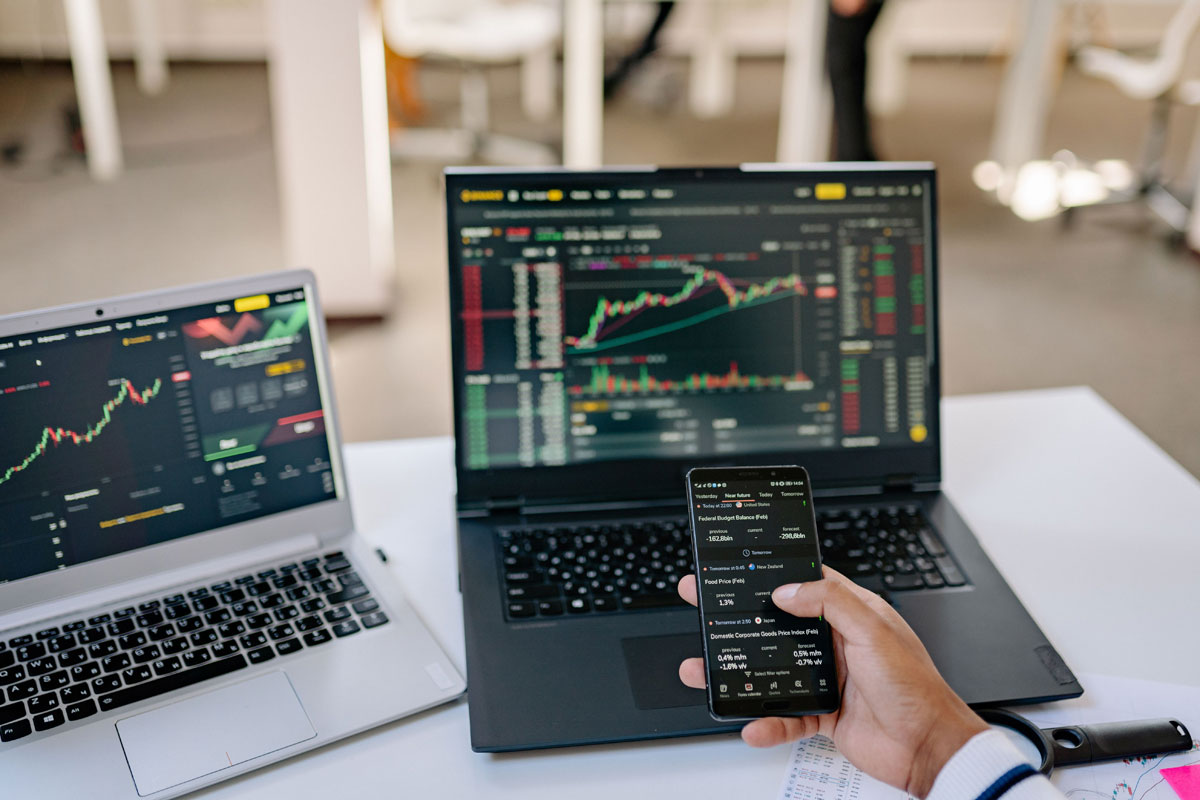
Investing is one of the most talked-about uses of AI, and it makes sense. Financial markets produce enormous amounts of data, and AI is good at processing it quickly. Still, these tools should support judgment, not replace it.
Robo-advisors use algorithms to build and manage portfolios based on goals, age, and risk comfort. They usually invest in diversified funds instead of individual stocks, which keeps things simple for long-term investors.
A major advantage is automatic rebalancing. If one part of the portfolio grows too large, the system can adjust the allocation back toward the target mix. Some platforms also offer tax-loss harvesting, which may help reduce taxes in taxable accounts.
For many people, that is enough. We get a structured investment approach without needing to study every market move.
Some investors prefer to choose individual companies, and AI can still help there. Research platforms can scan earnings reports, financial news, analyst notes, and market trends, then summarize the most important points.
These tools may also highlight changes in sentiment, unusual trading activity, or new risks tied to recent events. That can save a lot of time, especially when we want to compare several companies without reading every source from scratch.
Still, these tools should be used as research assistants. They can speed up the process, but they cannot fully replace context, long-term thinking, or human judgment.
Another useful category is portfolio optimization software. These tools look at how assets behave together and show where the portfolio may be too concentrated. A portfolio can look diversified at first glance, while still carrying too much risk in one industry, region, or asset type.
AI can help reveal those weak spots and suggest a better balance based on goals. This is especially useful for people who have accounts spread across different platforms and need a clearer overall picture.
Credit and debt can be stressful because they often involve both numbers and emotions. AI helps by making the process clearer and more organized.
Credit monitoring apps do more than show a score. Some use AI to explain why the score changed, which accounts may have caused it, and what actions could help improve it.
That context matters because a score shift without explanation can create confusion. If we are planning a mortgage, car loan, or refinance, these tools can help us keep an eye on our credit and catch errors sooner.
AI debt tools look at balances, interest rates, and monthly payments, then suggest a repayment plan. Some compare popular approaches like the snowball method, which focuses on smaller balances first, and the avalanche method, which targets high-interest debt first.
The useful part is flexibility. If our income changes or expenses rise, the tool can adjust the plan and show us what still makes sense. That kind of adaptability can keep us moving forward even when life gets messy.
Taxes are often stressful not because the math is impossible, but because the paperwork is scattered. AI helps reduce that chaos.
Modern tax software often uses AI to scan documents, identify deductions, sort income, and fill out forms faster. For people with simple returns, this can make filing much less painful.
The benefit is not just speed. These systems can also flag missing data or entries that deserve another look before we submit anything.
For self-employed people, AI expense tracking tools are especially helpful. They can sort business and personal spending, organize receipts, and remind us about categories that matter at tax time.
That makes a big difference when tax season arrives. Instead of scrambling through statements, we can keep records organized throughout the year and avoid last-minute stress.
Security is one of the strongest use cases for AI in finance. Fraud can happen quickly, and pattern recognition can help catch it sooner.
Banks and payment apps already use AI to watch for strange activity. If a charge appears in a new location, at an unusual time, or far outside our normal spending pattern, the system may send an alert or ask us to confirm it.
That speed matters. The sooner fraud is caught, the easier it is to stop charges, freeze an account, or reset access before more damage is done.
Some platforms go beyond account monitoring and look for signs that personal information may be exposed. They can scan for data breach alerts, suspicious activity, or signs that our details are being used where they should not be.
Identity theft can spread across many parts of life, so early warnings are valuable. They give us a better chance to respond before the problem becomes harder to fix.
Some tools focus less on current spending and more on what may happen next.
Forecasting tools study past income and expenses to predict future balances. This is especially useful for freelancers, contractors, and anyone with irregular income.
If the tool sees a tight month ahead, we can prepare early. That might mean shifting a bill, delaying a nonessential purchase, or moving money before a shortfall appears.
Retirement calculators have also become more advanced with AI features. Instead of relying on a basic formula, some tools review spending habits, income, savings rate, age, and possible market conditions to estimate whether we are on track.
They can also show how different contribution levels affect the future. That makes retirement planning feel more practical, because we can see how small changes today may shape the bigger picture later.
Not every AI tool is worth using, even if the marketing sounds impressive. A good financial app should fit our habits and make life easier, not more confusing.
If a tool is hard to understand, we probably will not stick with it. Clear menus, simple setup, and useful visuals matter more than flashy features that never get used.
Any tool that connects to financial accounts should use strong protection. Encryption, two-factor authentication, and clear privacy policies are essential.
AI can make mistakes. We should check whether spending categories, predictions, and recommendations actually fit our situation. If the basics are wrong, the tool may not be reliable for bigger decisions.
The best tools adapt to our goals. We should be able to change categories, adjust alerts, and customize settings instead of forcing our money life into a rigid template.
Some apps are free, while others charge monthly fees. The real question is whether the value we get is worth the cost.
AI is helpful, but it is not perfect. It cannot fully understand our values, emotions, family needs, or long-term priorities. It also cannot predict every market change or life event.
A tool may misclassify a transaction. It may overreact to short-term market noise. It may suggest something efficient that does not fit our actual life.
For example, the mathematically best debt strategy may not be the one that keeps us motivated. A portfolio that looks optimal on paper may still feel wrong for our comfort level.
That is why human judgment still matters. AI can make the numbers easier to understand, but we decide what those numbers mean for our lives.
AI has already changed personal finance in useful ways. It helps us budget with less effort, save more consistently, invest with better structure, and protect our money from fraud. It can also simplify taxes, support debt repayment, and make long-term planning easier.
The best tools are not the ones that try to take over. They are the ones that help us understand our money more clearly and act with more confidence. When we choose tools that match our goals, protect our data, and provide useful information, AI becomes less of a trend and more of a practical advantage in everyday life.


Discover our other works at the following sites:
Danetsoft is a global web agency headquartered in Indonesia, specializing in web development, managed hosting, and web publishing platform.


 [email protected]
 Magelang, Central Java
© 2026 Danetsoft. Powered by HTMLy